From Lower Payments to Cash-Out: Why Refinancing Could Be the Smart Move for You
A mortgage refinance is the process of replacing your current mortgage with a new one, typically to take advantage of better terms. Homeowners often choose to refinance their mortgages to reduce their interest rates, lower monthly payments, or adjust the term of the loan. It’s an attractive option, particularly when interest rates are dropping, as it offers the potential to save money over time.
Why Consider Refinancing Now?
With interest rates currently decreasing, refinancing can be a smart financial move. Here are a few key benefits:
- Lower Monthly Payments: Refinancing at a lower interest rate reduces your monthly mortgage payments, freeing up cash for other expenses or savings.
- Eliminate or Reduce Private Mortgage Insurance (PMI): If you initially purchased your home with less than a 20% down payment, you likely had to pay PMI. Refinancing, especially when your home’s value has increased, can help eliminate or reduce this extra cost.
- Shorten the Loan Term: Some homeowners refinance to move from a 30-year mortgage to a 20, 15 or 10 year mortgage. While monthly payments may increase slightly, a shorter loan term can save significant interest over the life of the loan.
- Cash-Out Refinancing: If you have built up equity in your home, a cash-out refinance allows you to borrow against that equity to fund other needs, such as home improvements or paying off high-interest debts.
How Does Refinancing Work?
Refinancing involves applying for a new mortgage loan. Once approved, the new loan pays off the balance of your current mortgage, effectively replacing it. The steps include working with a mortgage loan originator, gathering necessary financial documents, and undergoing a home appraisal.
What is the Role of a Real Estate Law Firm in Refinancing?
A real estate law firm plays a critical role in the refinancing process. Just like when you first purchased your home, an attorney ensures all legal aspects of the transaction are handled correctly. They review the terms of the new mortgage, manage the closing process, conduct an updated title search and ensure that title issues, if any, are resolved.
An important consideration during refinancing is whether you need a new lender’s title insurance policy. This policy protects the lender against any claims or issues that may arise with your property’s title, and in most cases, a new policy is required when refinancing with a different lender.
Evaluating the Costs of Refinancing
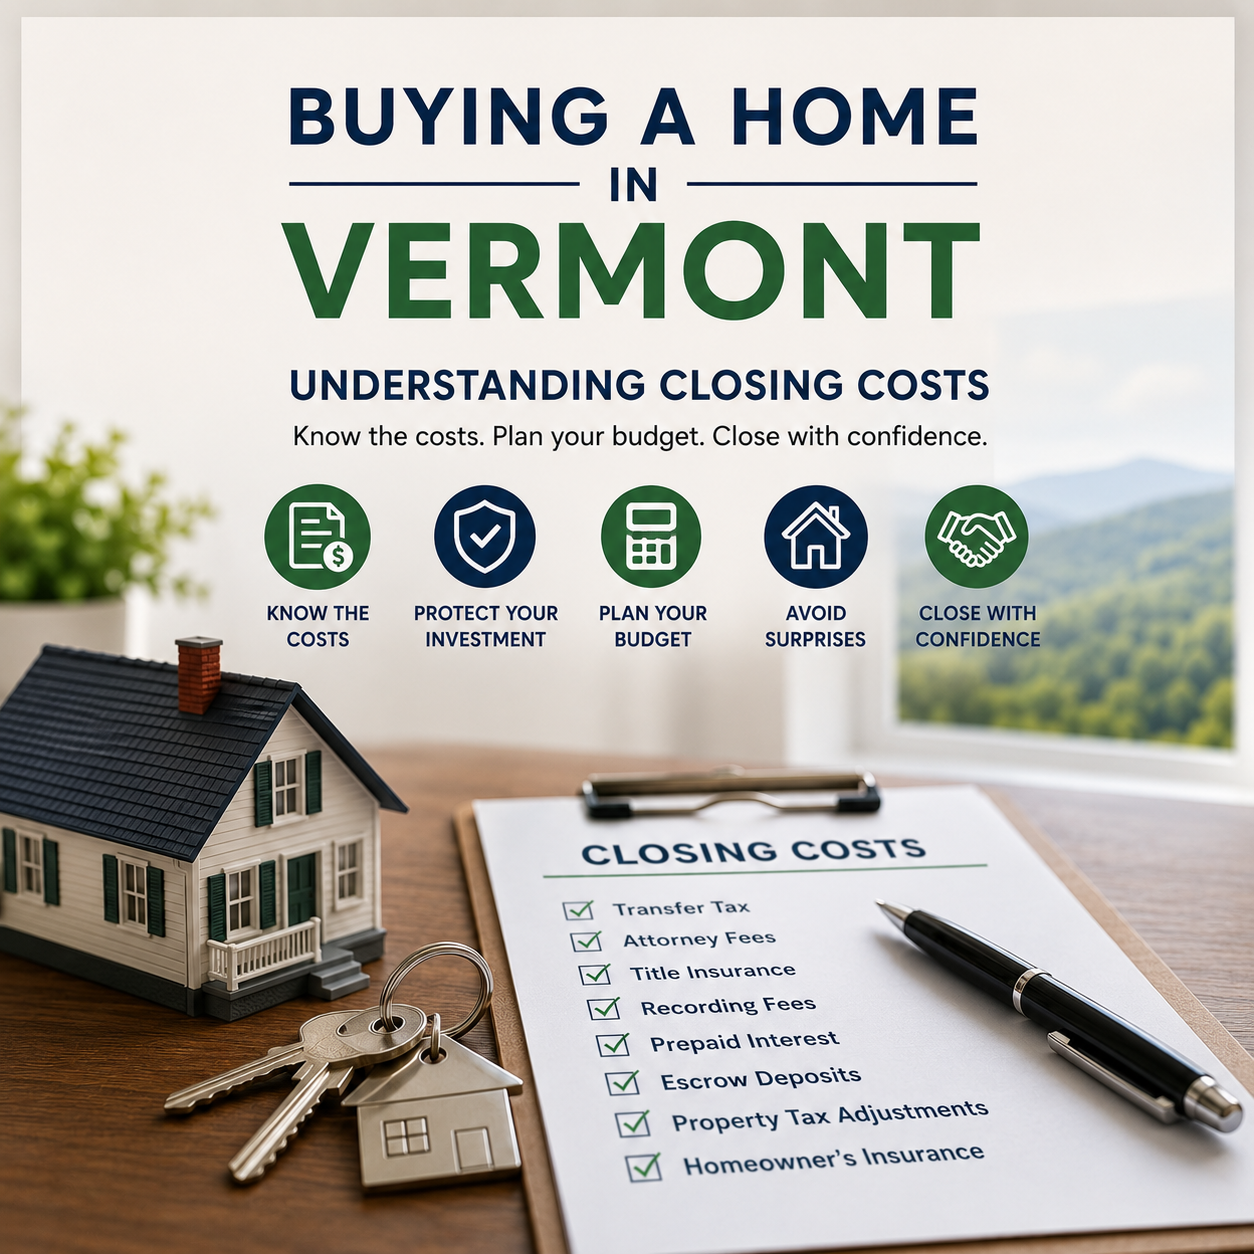
Refinancing comes with closing costs, similar to when you first bought your home. These costs can include application fees, appraisal fees, recording fees, attorney fees, and title insurance, among other expenses. It’s important to evaluate how long it will take to recoup these costs through the savings from lower payments. Generally, if you plan to stay in your home for a few years after refinancing, the long-term savings can outweigh the upfront costs.
Some lenders offer no or low closing cost programs to make refinancing more accessible. These programs may roll the costs into the loan balance or increase the interest rate slightly to cover the fees. It’s important to weigh these options carefully to determine the most cost-effective approach for your situation.
Start the Process with a Mortgage Loan Originator
If you’re considering refinancing your mortgage, your first step should be to contact a mortgage loan originator. They will help you explore your options, provide a breakdown of potential savings, and guide you through the process.
Refinancing can be a great way to improve your financial situation, and with the help of an experienced real estate law firm, the process can be smooth and straightforward. Be sure to evaluate your long-term plans, compare lenders, and consider how soon you’ll break even on the closing costs to make the best decision for your future.